Key points at a glance
- WZW stands for effective, appropriate and cost-effective (the German initials); under Art. 32 para. 1 KVG, effectiveness must be scientifically proven.
- Under Art. 32 para. 2 KVG the three criteria are reviewed periodically; medicines on the List of Pharmaceutical Specialties every three years (Art. 65d KVV).
- Basic health insurance does not reimburse benefits that fail to meet the criteria in an evidence-based procedure (Art. 32 para. 4 KVG).
- Doctors, therapists and hospitals must limit themselves to what is necessary for the purpose of the treatment (Art. 56 para. 1 KVG).
What are the WZW criteria?
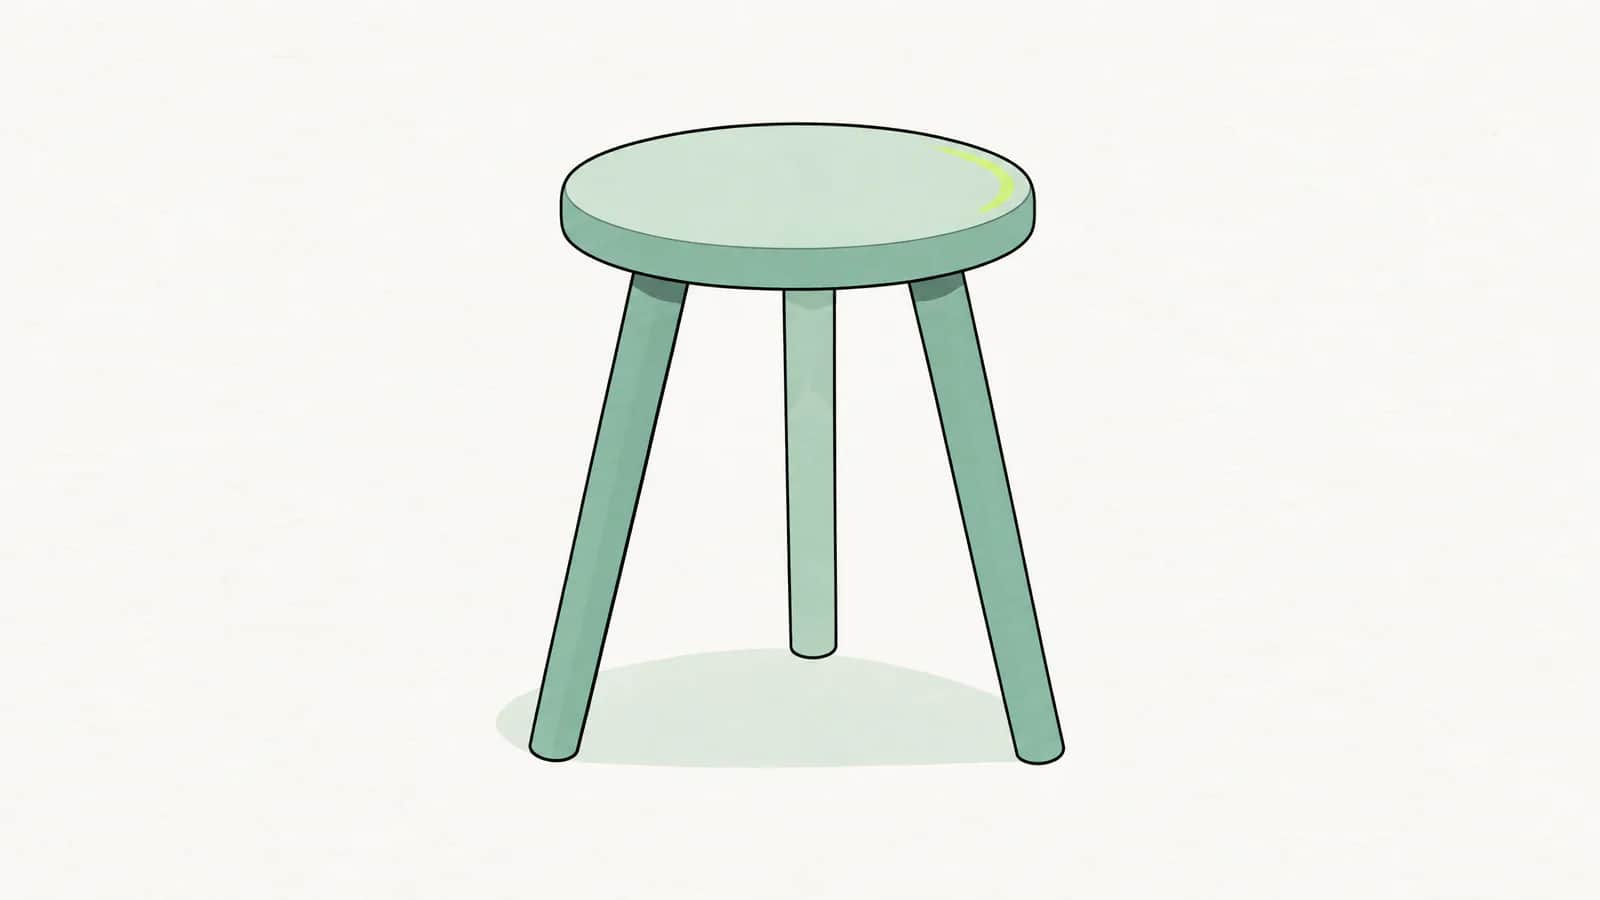
The WZW criteria are the yardstick against which every benefit of compulsory health insurance must be measured. The three letters are the German initials for effective, appropriate and cost-effective. Basic health insurance only pays for a treatment, a medicine, a laboratory analysis or an aid or appliance if all three conditions are met at the same time. You can think of the criteria as the three legs of a stool: if one is missing, the benefit does not stand.
The criteria apply to compulsory health insurance, in other words to basic health insurance under the Health Insurance Act (KVG). They determine what is included in the benefits covered by compulsory health insurance and what is not. Supplementary insurance under the Insurance Contract Act (ICA) has no such statutory limit; there, the contract decides.
What the three terms mean:
- Effective means that the benefit can achieve the intended medical goal. The law requires effectiveness to be proven by scientific methods.
- Appropriate means that the benefit is suitable for the specific illness and that its benefits outweigh its risks. An effective therapy can still be inappropriate in a particular situation.
- Cost-effective means that costs and benefits are in a reasonable relationship. If there are two equally good options, the cheaper one must be chosen.
How it works
The WZW check takes place at two levels. At system level, the Confederation decides which benefits belong to basic health insurance at all. For example, the FOPH maintains the List of Pharmaceutical Specialties, which contains all medicines covered by health insurance and their maximum prices. A medicine is only added to the list if it is authorised by Swissmedic and meets the WZW criteria. The FOPH checks cost-effectiveness using, among other things, a comparison with prices abroad and a therapeutic comparison with similar medicines. The conditions for listing are reviewed every three years.
Medical services by doctors are in principle covered by health insurance unless they are expressly excluded or restricted. The Confederation and the advisory commissions can review disputed benefits. Services not provided by doctors, such as physiotherapy or nutritional advice, are described exhaustively in the Health Care Benefits Ordinance (KLV), often with limits on quantity. For physiotherapy, for example, the insurer covers at most nine sessions per medical prescription.
At the individual level, your health insurer checks whether a specific bill corresponds to what was necessary for the purpose of the treatment. For expensive or lengthy treatments it involves its medical adviser. The medical adviser sees the medical records and gives the insurer a recommendation without passing on details of the diagnosis to the administration.
Legal basis
Art. 32 para. 1 KVG states that the benefits under Art. 25–31 KVG must be effective, appropriate and cost-effective, and that effectiveness must be proven by scientific methods. Under para. 2, the three criteria are reviewed periodically. Para. 3 and 4 require benefits for which there are indications that the criteria are not met to be evaluated in an evidence-based procedure and, if the result is negative, no longer reimbursed.
Art. 33 KVG empowers the Federal Council to designate benefits that are not covered or only covered under certain conditions, and to set up advisory commissions for this purpose. Art. 56 para. 1 KVG requires service providers to limit themselves to what is in the interest of the insured person and necessary for the purpose of the treatment; para. 2 allows reimbursement for benefits going beyond this to be refused. For medicines, Art. 65 ff. of the Health Insurance Ordinance (KVV) govern listing in the List of Pharmaceutical Specialties and the review every three years (Art. 65d KVV).
Example: physiotherapy for back pain
Lea, 41, has had recurring back pain for months, without any preceding accident. Her GP prescribes physiotherapy, which is covered by basic health insurance. The table shows how the WZW criteria shape the process.
| Step | What happens | Link to WZW |
|---|---|---|
| 1. Prescription | The doctor issues a prescription. | The insurer covers at most 9 sessions per prescription (Art. 5 para. 2 KLV). |
| 2. First series | 9 sessions, the first within 5 weeks of the prescription. | Appropriate and effective according to the prescription. |
| 3. Further series | A new prescription for each further series. | After 36 sessions, a report to the medical adviser is required (Art. 5 para. 4 KLV). |
| 4. Review | The medical adviser assesses whether further therapy is necessary. | Cost-effectiveness in the individual case. |
What this means for you
You do not have to check the WZW criteria yourself, but they explain many of your insurer’s decisions. Three points help you in everyday life:
- Ask for cost approval before expensive treatments. If it is unclear whether a benefit will be paid for, your doctor can have your insurer check in advance.
- For medicines, look at the List of Pharmaceutical Specialties. As a rule, only products on the list are covered by health insurance. Cheaper generics often lower your retention fee.
- Ask for a written decision if you are refused. Your insurer must tell you in writing, with reasons, why it is not paying. You can lodge an objection against it.
Because the benefits covered by basic health insurance are the same at every insurer, insurers mainly differ in basic health insurance through the premium. The premium calculator compares all offers for where you live. You can find key figures on the individual insurers under health insurers.
Common mistakes
- Confusing WZW with “as cheap as possible”. Cost-effective does not mean cheap, but a reasonable relationship between benefit and cost. An expensive therapy can be cost-effective if there is no equivalent alternative.
- Believing every medical prescription is automatically covered. Prescribed benefits must also be included in the benefits catalogue and stay within the limits on quantity.
- Mixing up supplementary and basic health insurance. The WZW criteria only apply under the KVG. What a supplementary insurance pays for is set out in its conditions.
- Simply accepting a refusal. Without a written decision you cannot challenge it. In a dispute, the Office of the health insurance ombudsperson helps free of charge.
We explain how we present benefits and costs under How we calculate.
Frequently asked questions
What does WZW mean in health insurance?
WZW stands for effective, appropriate and cost-effective. Basic health insurance may only pay for benefits that meet all three conditions. The rule is set out in Art. 32 KVG.
Who checks whether a benefit meets the WZW criteria?
Which benefits are paid for in principle is determined by the Federal Council, the Federal Department of Home Affairs and the FOPH after consulting advisory commissions. In individual cases, your health insurer checks, often with its medical adviser, whether a specific treatment was necessary and appropriate.
Can my health insurer refuse a treatment because of WZW?
Yes. If a benefit goes beyond what is necessary for the purpose of the treatment, the insurer can refuse reimbursement under Art. 56 para. 2 KVG. If you do not agree, ask for a written decision; you can then lodge an objection against it.
Do the WZW criteria also apply to supplementary insurance?
No, not as a statutory rule. Supplementary insurance is governed by the Insurance Contract Act (ICA). What it pays for is set out in the contract conditions of each insurer.
Related terms
- Benefits catalogue of basic health insuranceThe benefits catalogue of basic health insurance sets out which treatments, medicines, analyses and aids and appliances every health insurer must pay for. It is laid down in Art. 25–31 KVG and specified in the KLV and three federal lists. It is the same at every insurer; basic health insurance may not pay for more than these benefits.
- List of Pharmaceutical Specialties (SL)The List of Pharmaceutical Specialties (SL, Spezialitätenliste) is the Federal Office of Public Health’s list of all medicines paid for by basic health insurance, together with their maximum prices. A medicine is only added if Swissmedic has authorised it and it is effective, appropriate and cost-effective. As a rule, basic health insurance does not pay for anything that is not on the SL.
- Medical adviserThe medical adviser of the insurer (Vertrauensarzt) advises the health insurer on medical questions and checks whether it must pay for a benefit under basic health insurance. The adviser is independent in their judgement and only passes on to the insurer the information it needs for its decision. For psychotherapy, for example, the adviser reviews whether it continues after 40 sessions.
- Compulsory health insurance (OKP)OKP stands for obligatorische Krankenpflegeversicherung, compulsory health insurance, which people usually call basic health insurance. Everyone resident in Switzerland must take it out within three months. The benefits are laid down in the Health Insurance Act (KVG) and are the same with all 34 approved insurers; you only choose the insurer, deductible and model, and pay a premium plus co-payments.
- KLV (Health Care Benefits Ordinance)The KLV, the Health Care Benefits Ordinance, sets out which benefits basic health insurance covers, under what conditions and up to what amount. It is issued by the Federal Department of Home Affairs. For example, it provides that the insurer pays 50% of the cost of rescues in Switzerland, up to CHF 5,000 a year.
Sources
- Federal Health Insurance Act (KVG), Art. 32Art. 32 KVGfedlex.admin.ch
- Federal Health Insurance Act (KVG), Art. 56Art. 56 KVGfedlex.admin.ch
- Federal Health Insurance Act (KVG), Art. 33Art. 33 KVGfedlex.admin.ch
- Health Insurance Ordinance (KVV), Art. 65–65dArt. 65–65d KVVfedlex.admin.ch
- Health Care Benefits Ordinance (KLV), Art. 5Art. 5 KLVfedlex.admin.ch
- FOPH: List of Pharmaceutical Specialtiesspezialitaetenliste.ch